A purchase is not the only outcome
I explain the trade-offs and the limits of a recommendation. Some cases end without a purchase, or with the existing coverage left in place.

About Caleb Dupae
I run an independent insurance brokerage from Austin, built for referrals from fee-only advisors and the clients they send.
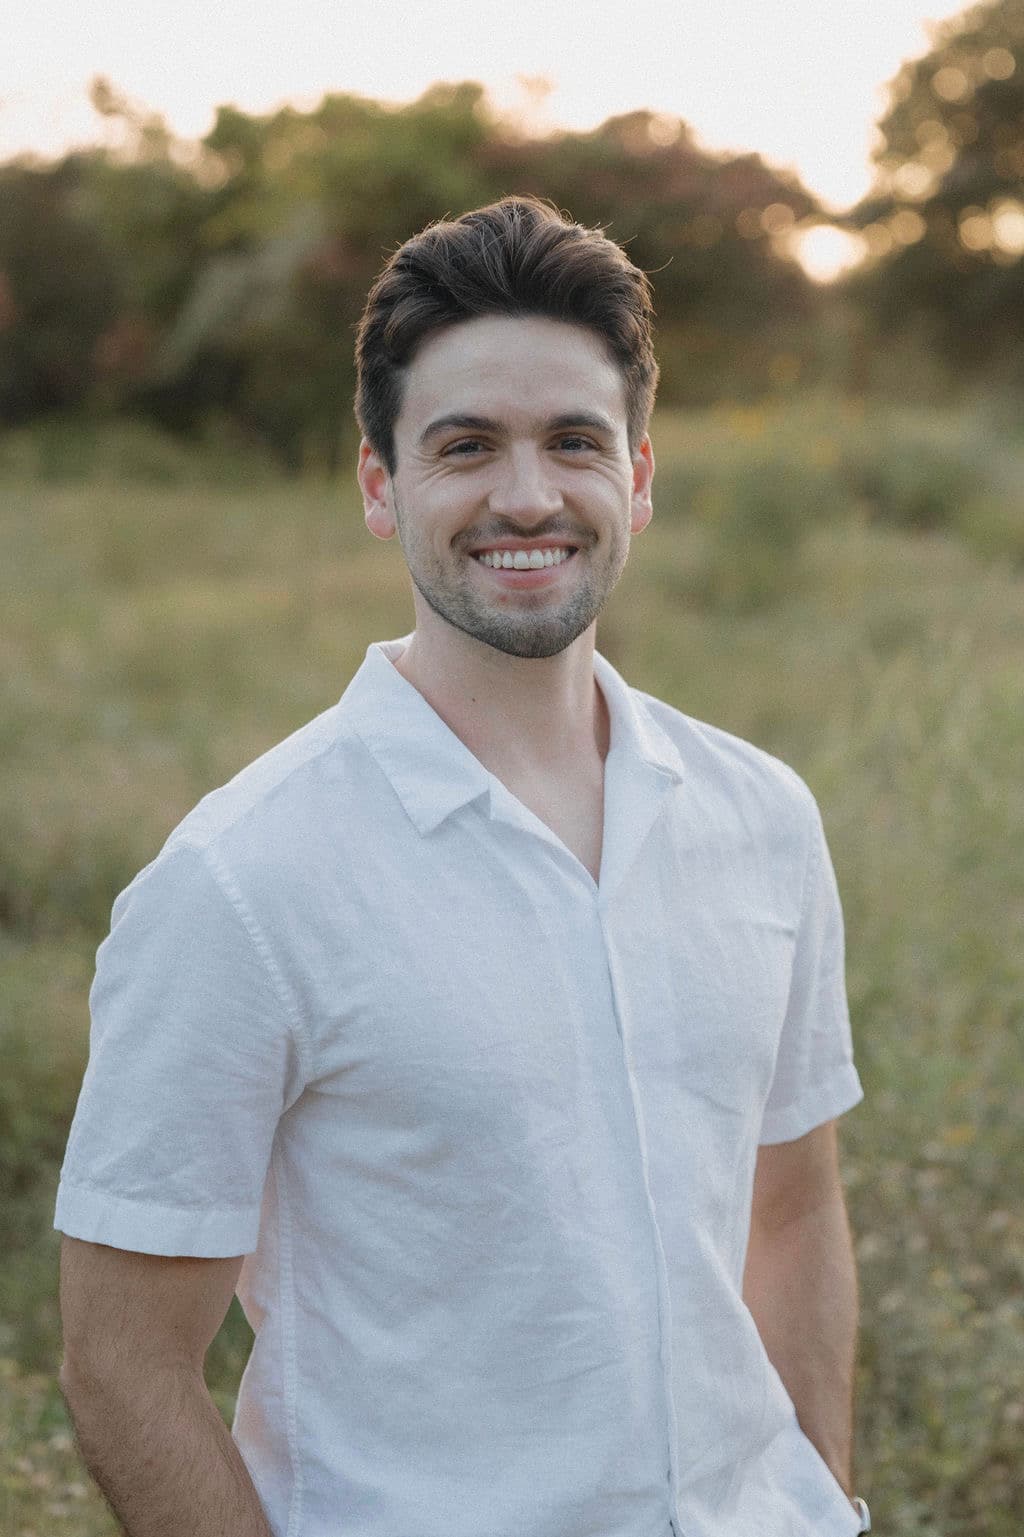
Caleb Dupae
Founder, Aligned Path Insurance Solutions
Austin, Texas
Licensed insurance producer. Texas resident license, NPN 20750662.
Background
A friend who is a fee-only financial advisor asked whether I would consider starting an insurance brokerage. He wanted somewhere to refer clients that would follow his coverage recommendation without pitching unrelated products or taking over the relationship.
Before insurance, I was a platform developer at Kwik Trip in Wisconsin, where I built workflow systems for teams that were still doing a lot of the work by hand. Earlier, I worked on projects in fire protection and building products. Those jobs were pretty practical. I usually had to spend time with the people doing the work because I could not build anything useful until I understood where they were getting hung up.
These days, most of my week is spent in underwriting and coverage details. I go through health histories early because a condition one carrier is comfortable with can be a problem for another. With disability coverage, I need to understand exactly how the person is paid before I can structure the policy. I also read the home and auto policies alongside the umbrella and look for places where the coverage does not line up.
Outside the work
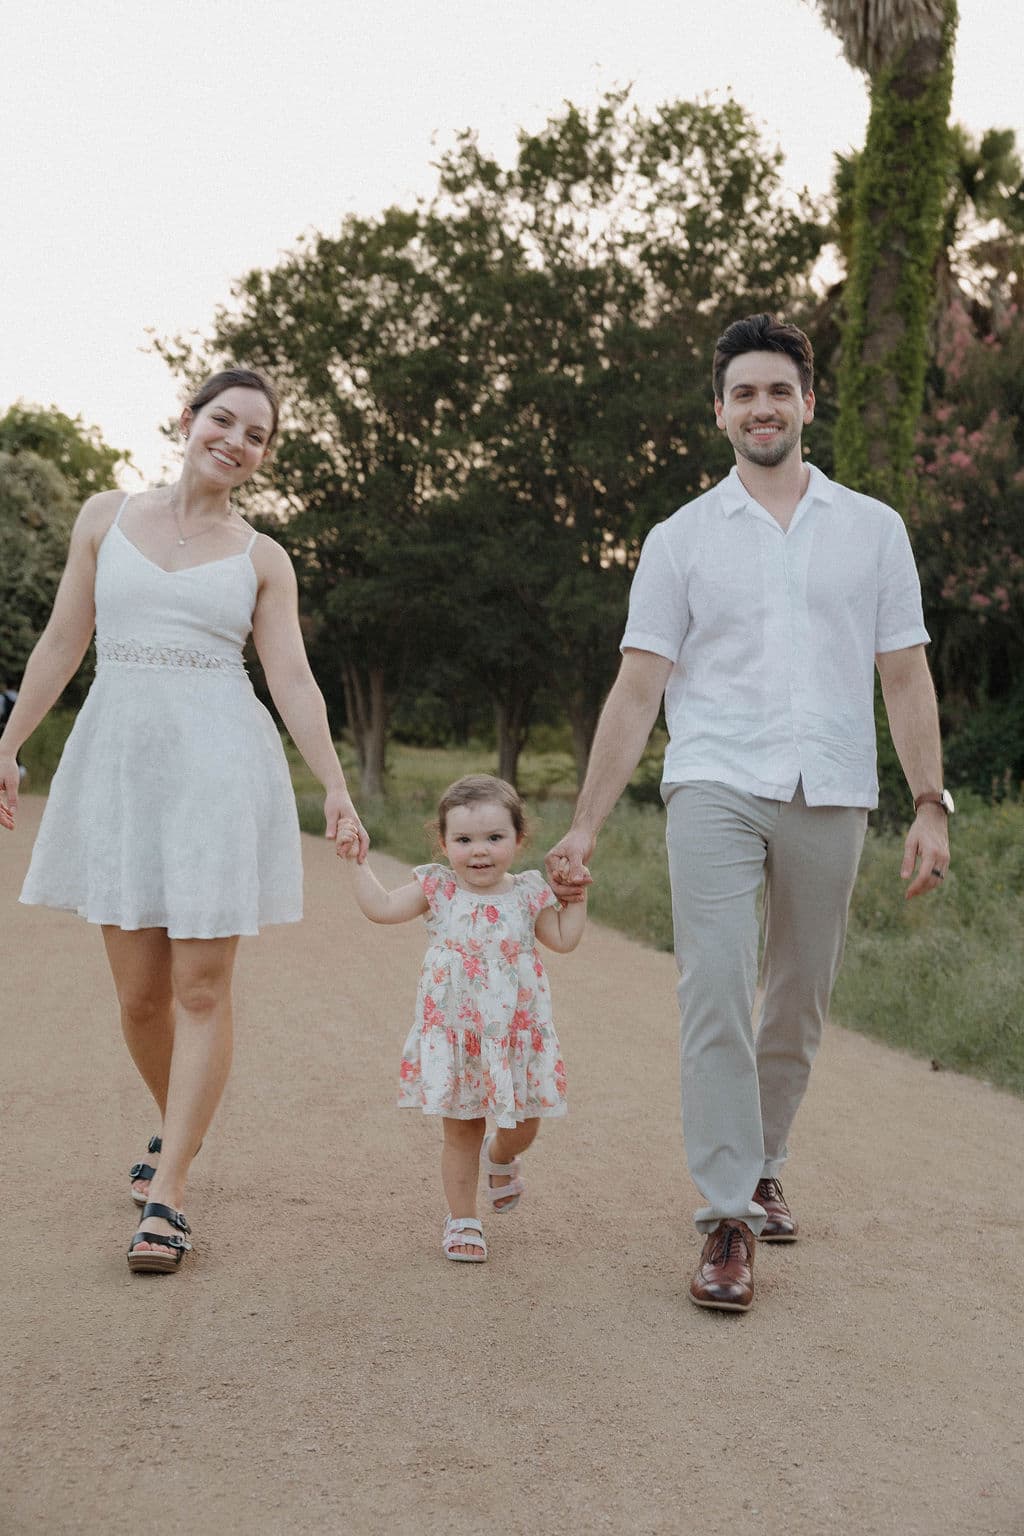
My wife and I moved down from Wisconsin a few years ago. Most of what happens outside work goes to our daughter, who is at the age where a walk around the block is a forty-minute expedition.
I grew up in Wisconsin and went to UW-La Crosse, which is why the phone number still starts with 608. I also speak Spanish, which comes up more often on a property and casualty call than you'd expect.
I lead the client work. For property and casualty and for life underwriting I work with dedicated brokerage desks, and for complex long-term care and business cases I bring in advanced-markets specialists. Those relationships are where the carrier access comes from, and I only place coverage with carriers that meet a minimum financial strength standard.
See the carrier standardI explain the trade-offs and the limits of a recommendation. Some cases end without a purchase, or with the existing coverage left in place.
I keep the advisor informed from quoting through underwriting and delivery. If anything material changes, I call or email.
I built Aligned Path around referrals from planners whose clients pay them directly for advice. The advisor makes the planning recommendation, and I handle the insurance work that follows.
The company started out as Fiduciary Insurance Advisor. I changed it because I am not a fiduciary and Aligned Path is not fee-only: when a policy is placed, the carrier pays me a standard commission, and the referring advisor earns none of it.
If you don't have an advisor yet, organizations like NAPFA, the XY Planning Network, the Garrett Planning Network, FeeOnlyNetwork, and the Advice-Only Network maintain public directories of fee-only planners.
See our guide to finding a fee-only advisor